Most advisors who handle U.S. real estate for owners living abroad never mention FIRPTA — until the closing statement arrives. On a $1M sale, that is $150,000 withheld before you see a cent. Three legal strategies can eliminate or significantly reduce it, depending on your facts — but only if you act before closing.
Licensed Real Estate Broker (IL) · Sales Agent (TX) · Equal Housing Opportunity
For Established Investors Managing Serious Capital Across Borders

The IRS Is Waiting
at Your Closing Table.

What most established investors managing serious capital do not know: FIRPTA requires 15% of your entire gross sale price — not your profit — to be withheld at closing. On a $1,000,000 sale, that is $150,000 held by the IRS before you see a cent. Three legal strategies exist to eliminate or significantly reduce it — but all three require deliberate action before closing, not after.

How the Simultaneous Exchange Works
"FIRPTA withholds 15% of your entire sale price at closing — not your profit. On a $520,000 sale that's $78,000 gone before you see a cent. The simultaneous 1031 exchange is one of three legal structures that can eliminate it entirely — but only if you structure before closing."
Foreign National Investors · Three Legal Strategies · Must Be Structured Before Closing
15%
FIRPTA withholding rate on your entire sale price — not just your profit
$481K+
What $150,000 becomes at 6% over 20 years — the true cost of FIRPTA
$0
What FIRPTA withholding can become with the right strategy, structured in advance — depending on your individual facts

Figures are illustrative projections for educational purposes. Individual outcomes vary based on transaction facts, timing, rates, and IRS determinations. Not a guarantee of any specific tax or financial outcome.

Get the free withholding check

Two situations. One critical decision.

🏢
You already own U.S. property

You've been building equity and now you're ready to sell and reinvest. But without the right structure in place before closing, 15% of your entire sale price disappears on day one — not your profit, your gross proceeds. The good news: there are three paths to keep it.

Existing Owner
🌍
You're acquiring U.S. property for the first time

Most established investors managing serious capital who purchase U.S. real estate for the first time set up their ownership incorrectly — and inherit a FIRPTA liability they won't discover until they try to sell. The time to eliminate it is before your first closing, not after. The investors who know this are a step ahead of those who don't.

Pre-Purchase
Get the free withholding check

If you are a U.S. citizen or permanent resident, FIRPTA does not apply to you as a seller. Your real estate attorney handles this at closing as a standard step. This check is not written for your situation.

If you have never owned U.S. real estate and are not planning to acquire it within the next eighteen months, the withholding mechanics here are not immediately actionable for you. Bookmark it for when the timeline gets real.

If you are already working with a U.S.-based international tax attorney who has handled FIRPTA compliance for foreign sellers, you may already have this covered. Ask them specifically about IRS Form 8288, withholding certificates, and 1031 exchange eligibility before assuming.

If you have less than $200,000 in liquid capital across your portfolio, the strategies in this guide are not yet actionable for your situation.

If none of those apply — keep reading. FIRPTA is not complicated when you understand it before you need it. It becomes complicated when you find out at the closing table.

Holding part of what you built outside one country and one currency.

Investors from Africa, Asia, Europe, Latin America and the Middle East hold U.S. property for the same reason: it pays in dollars and it sits outside the cycles of any one home currency. NAR counted 67,100 U.S. homes bought by foreign buyers in the year to March 2026 — 44% of them by buyers living abroad. The question is not whether U.S. property makes sense. It is whether you are set up to keep what you build when you sell. FIRPTA applies no matter where your money started.

Patrick leads the home side from the first call to closing day, and takes on a few new clients a month.

There is no single FIRPTA solution. There are three paths.

Which path applies to you depends on your timeline, whether you've found a replacement property, and whether you apply before closing. All three require an ITIN and a Qualified Intermediary who specifically understands FIRPTA — not all QIs do. Not buying again? A withholding certificate on its own (Form 8288-B), filed before closing, can still cut the hold to the tax you actually owe. The check walks you through that question first.

02
Delayed Exchange + Withholding Certificate
Reduced or Eliminated

Standard 45-day/180-day timeline. You apply to the IRS for a withholding certificate before your first closing. If approved, FIRPTA is reduced or eliminated. Requires early application — IRS processing is currently experiencing delays.

03
Delayed Exchange, No Certificate
15% Withheld Upfront

The 45/180-day timeline applies, but no certificate was requested. FIRPTA is withheld in full at closing. Those funds do not enter the exchange — you must add cash out of pocket to complete it, or accept a partial exchange with taxes due on the shortfall.

⚠️ An LLC does not bypass FIRPTA. A U.S. LLC owned by a single foreign national is still subject to FIRPTA withholding. Structure matters — get it right before closing.

Get the free withholding check

The right structure, decided before closing.

Most owners living abroad discover FIRPTA at the closing table — too late to act. The three strategies below can eliminate or significantly reduce withholding, but each one must be in place before your first closing date. Here's what each path looks like in practice.

Simultaneous Exchange
Sell and buy on the same day
Path 1
Example sale price $520,000
FIRPTA if unstructured −$78,000
FIRPTA when structured in advance $0
Example replacement property 6-unit building at $720,000
$78,000 at 6% over 20 years ≈ $250,000 compounding

In a simultaneous exchange, both closings happen on the same day through a FIRPTA-experienced Qualified Intermediary. When structured correctly before closing, withholding can be eliminated entirely — no refund petition, no waiting. The replacement property must be identified and ready before the first closing date.

Compounding figure is illustrative at an assumed 6% annual rate and is not a projection of actual investment returns. Individual results depend on reinvestment rate, timing, and market conditions.

Legacy Exchange
Long-term hold + estate planning
Long-Term Strategy
Example sale price $1,800,000
FIRPTA if unstructured −$270,000
FIRPTA when structured in advance $0
Step-up in basis at inheritance Deferred gains eliminated

Foreign national investors who hold appreciated U.S. property long-term can combine a 1031 exchange with estate planning to defer capital gains across successive exchanges. When heirs inherit at market value, the step-up in basis can eliminate the deferred capital gain, depending on individual facts. U.S. estate tax is a separate exposure — see the next section — and has to be planned for in the same structure. Requires advance planning with a qualified intermediary and estate attorney; individual outcomes depend on applicable facts and law.

FIRPTA planning options disappear at closing.
Once the deed transfers, so does your leverage.

The withholding certificate that allows a reduced rate — or no withholding at all — must be applied for before or at closing. The IRS processing window for Form 8288-B is 90 days. That is not a correction you can file after the fact.

A 1031 exchange — the strategy that defers capital gains entirely by rolling proceeds into the next U.S. property — requires a Qualified Intermediary in place before closing, a 45-day replacement property identification window, and a 180-day close. None of those timelines can be extended after the first closing happens.

Every FIRPTA option — the withholding certificate, the 1031, the ITIN application — has a decision point before the sale. The check puts each one on a timeline counted back from your closing date; the guide, two days later, has the detail.

The cost of reading this after closing is not embarrassment. It is withholding that does not come back.

FIRPTA is not the only tax event. Estate tax is the other one.

FIRPTA applies when you sell. Estate tax applies if you pass away while still owning U.S. property. The two are different rules, at different moments, and most foreign national investors have only ever heard of one.

U.S. citizen exemption
$15,000,000
Non-U.S. citizen exemption
$60,000

Above that $60,000, U.S. real estate owned by a non-citizen can be taxed at rates up to 40% before it passes to your family — without the right structure in place. This is a separate question from FIRPTA, and it gets answered before you buy, not after.

General information only, not individual tax or legal advice. Figures reflect current IRS rules for non-resident, non-citizen estates and are not adjusted for inflation. Estate tax treaties, ownership structure, and individual facts can change the outcome — consult a licensed estate attorney or CPA.

Most buyers living abroad find the financing. Then spend months searching for the right property with an agent who has never worked with a client living abroad before.

As a licensed real estate broker in Illinois and a licensed real estate sales agent in Texas, I lead the home side from anywhere to closing — Chicago and Texas; elsewhere I refer you to a licensed broker. I find the right property for your investment profile. I negotiate on your behalf. I coordinate the closing. When a loan is part of the plan, I bring in an independent lender who decides whether you qualify and handles the financing.

Licensed Real Estate Broker (IL) · Licensed Real Estate Sales Agent (TX)
Independent lender financing — when a loan is part of the plan, a separate lender checks whether you qualify and handles the loan
Full transaction management — property search, negotiation, lender introduction, remote closing
Get the free withholding check
Questions, answered

Short answers to the questions owners abroad ask before they sell.

What is FIRPTA withholding?
When an owner who lives outside the United States sells U.S. real estate, U.S. law generally allows 15% of the gross sale price, not the profit, to be held at closing as a deposit against U.S. tax. Any amount above the real tax comes back only after a U.S. tax return is filed, usually the following year.
How much is held on a $520,000 sale?
15% of $520,000 is $78,000, held at closing unless a withholding certificate from the IRS is in hand or the sale is structured as an exchange in advance. The 15% Withholding Check calculates your number from your own sale price.
Can FIRPTA withholding be reduced or avoided?
It can be reduced, and in some cases brought to zero, but only by steps taken before closing: a withholding certificate (IRS Form 8288-B) filed early, a same-day 1031 exchange, or a delayed exchange with a certificate. A CPA or attorney sets up any of these; Patrick flags the timing and introduces the professionals.
Does an LLC avoid FIRPTA?
No. A U.S. LLC owned by one person is disregarded for U.S. tax, so the sale is treated as the owner’s sale and the hold applies the same way. An LLC can matter for liability, privacy and how the property passes to family, but not for the hold.
What is the 15% Withholding Check?
A free two-page fillable PDF. Type your sale price and the hold fills in; three yes/no questions point to the path that fits; page two is the sell-from-abroad timeline counted back from your closing date. General information, not tax advice.

Get the Free
15% Withholding
Check

One page. Type your sale price and see what can be held at closing. Three questions point to your path, and the timeline on the back shows what has to happen, in order, before you sell. It downloads on the next page. The full FIRPTA Protection Guide follows by email two days later.

The 15% Withholding Check — your number, the three questions that point to your path, and the sell-from-abroad timeline. Fillable PDF; it downloads on the next page
By email on day 2: the FIRPTA Protection Guide — the Cheatsheet, the Planning Checklist and the full Playbook, with worked numbers, the ITIN process and the 45/180-day timelines
QI Interview Questions — ten questions to confirm a Qualified Intermediary has handled sales by owners living abroad, not just domestic ones
Compounding Cost Chart — what $150,000 withheld on a $1M sale becomes at 6% over 20 years: $481,000 permanently out of your portfolio

This guide is free. The investors who read it understand something most foreign nationals and immigrants discover too late: FIRPTA is not a surprise — it is a planning failure. The right advisor addresses it before your first closing, not at it.

"The investors who structured correctly before closing look back and see a decision that compounded for decades. The ones who didn't look back and see a number that never returned." — Patrick Afrifah
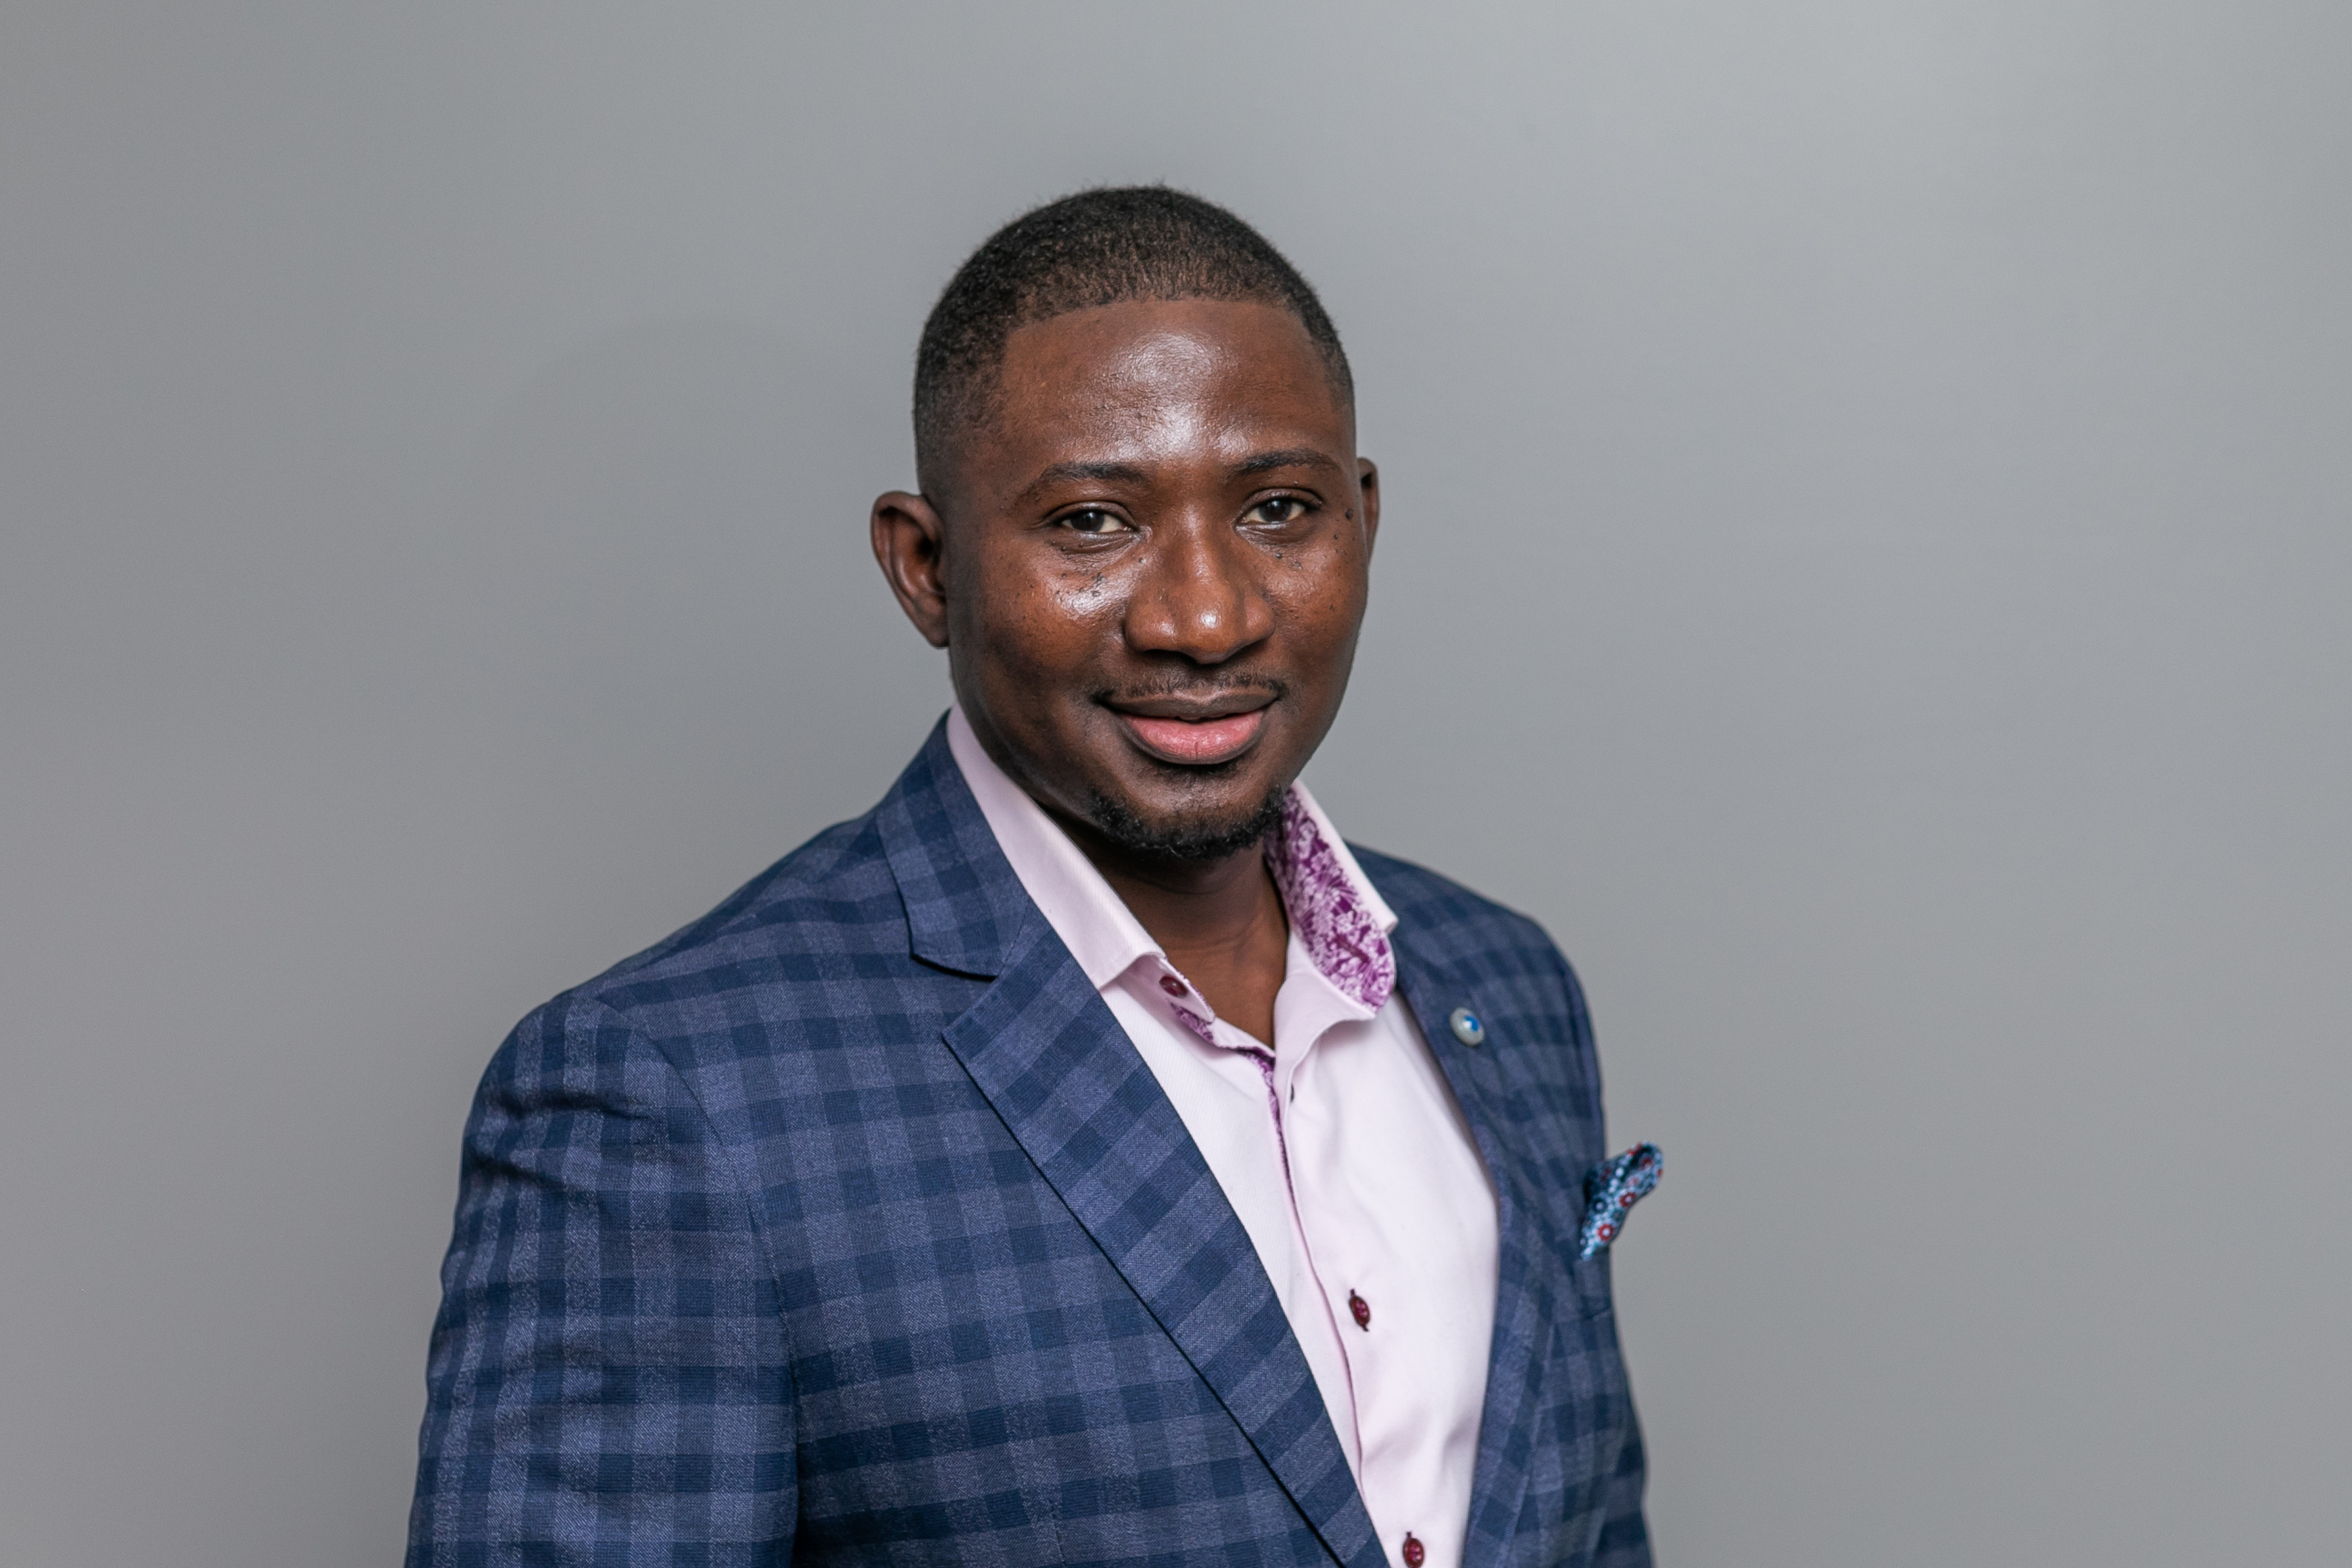
Patrick Afrifah
Patrick Afrifah
Licensed Real Estate Broker · Kale Realty (IL) | Licensed Real Estate Sales Agent · Central Metro Realty (TX) · TREC Lic. #848642-SA
Realtor® · Equal Housing Opportunity
Something went wrong. Please try again or WhatsApp us at +1 (773) 234-6382
You're in. Check your inbox for next steps.
The SMS field must contain between 6 and 19 digits and include the country code without using +/0 (e.g. 1xxxxxxxxxx for the United States)
?

This guide is designed for investors with $200,000+ in liquid capital ready to deploy.

By submitting, you agree to receive educational emails from Patrick Afrifah. No financial or credit information is collected here. Unsubscribe anytime.